
Tokenized deposits are not stablecoins
The current news cycle treats all digital money as a monolith. Between the Federal Reserve's GENIUS Act proposals and the push for interbank tokenization in the UK, the terminology has become a blur. Retail traders often assume a token is just a token, regardless of who issued it. This confusion raises a fundamental question: what are tokenized deposits crypto? We previously covered Open USD stablecoin for more background.
The short answer
Stablecoins are digital assets issued by private companies that are backed by reserves of cash or Treasuries. Tokenized deposits are digital representations of money already sitting in a regulated commercial bank account. One is a private IOU backed by collateral; the other is a bank liability.
How does what are tokenized deposits crypto work?
To understand the difference, you have to look at where the money actually lives.
When you hold a stablecoin like USDT or USDC, you hold a token issued by a private entity. That entity claims to hold a dollar in a vault or a Treasury bill for every token they mint. You are essentially holding a receipt for an asset the issuer owns. If the issuer disappears or the reserves are frozen, you are left holding a digital receipt for money you cannot touch.
A tokenized deposit is different. The money is already in a bank account. The bank simply issues a token that represents that specific deposit on a blockchain. The asset does not move from a bank to a "reserve"; it stays on the bank's balance sheet. You are not holding a receipt for an external asset. You are holding a digital version of your bank balance.
According to brookings.edu, payment stablecoins are a medium of exchange backed by liquid assets, while tokenized deposits are digital representations of deposits in regulated commercial banks. The difference is structural. One is a crypto asset; the other is a bank account with a blockchain skin.
The regulatory angle and the macro narrative
The market treats these two things very differently. We see this clearly when we score the news.
Regulatory proposals like the GENIUS Act are often framed as "progress" by the media. In reality, the market views them as compliance hurdles. These rules focus on capital requirements and redemption standards for private issuers. Our news scoring system rated this story 7/10 for novelty but 9/10 for liquidity impact. The high liquidity score reflects the risk that tighter rules could force stablecoin issuers to liquidate reserves or restrict how users move funds.
When we see the Fed proposing new reserve limits, it is not a catalyst for growth. It is a signal that the window for the "wild west" era of stablecoin issuance is closing.
Institutional adoption and real capital flow
While the regulators argue about rules, the banks are building the plumbing. This is where the actual utility lives.
The movement of assets through established banking rails is becoming more tangible. We see this in the scale of institutional appetite for tokenized structures. For example, we've tracked institutional capital movements hitting $2.34B across recent sessions in related tokenized vehicles. This is not just signaling. It is a shift in how capital moves.
Our news scoring system rated the adoption of institutional tokenization 9/10 for macro impact. We view this as a catalyst because it does not require a new regulatory regime to function. It simply uses the existing banking license and adds a blockchain layer to make settlement faster. We previously covered how European banks using stablecoins is an attempt to modernize cross-border payments, though it brings its own set of censorship risks.
Where people get tripped up
The biggest misconception is the assumption that all "stable" tokens carry the same risk. They do not.
First, there is the insurance gap. Stablecoins are not FDIC-insured. If Circle or Tether has a catastrophic failure, there is no government guarantee to save your USDC or USDT. Tokenized deposits, however, are issued by licensed banks. As noted by finovate.com, these deposits are typically regulated and insured by the FDIC.
Second, there is the counterparty risk. With a stablecoin, your risk is the issuer and their reserve management. With a tokenized deposit, your risk is the solvency of the bank. In a systemic banking crisis, a tokenized deposit is just as vulnerable as a traditional savings account.
Putting it into practice
If you are managing a portfolio, the distinction matters for your risk profile.
If you want a tool for DeFi and high-velocity trading, stablecoins are the only real option. They are designed for the open market. But if you are looking at institutional settlement or corporate treasury, tokenized deposits offer a level of regulatory safety that stablecoins cannot match.
Watch for the gap between the "regulatory noise" of the GENIUS Act and the "quiet plumbing" of bank tokenization. The noise is what the influencers talk about. The plumbing is where the money actually moves.
Some links in this article may be affiliate links. We may earn a commission at no extra cost to you — this never influences our analysis or coverage.
Sigrid Voss
Crypto analyst and writer covering market trends, trading strategies, and blockchain technology.
More Articles
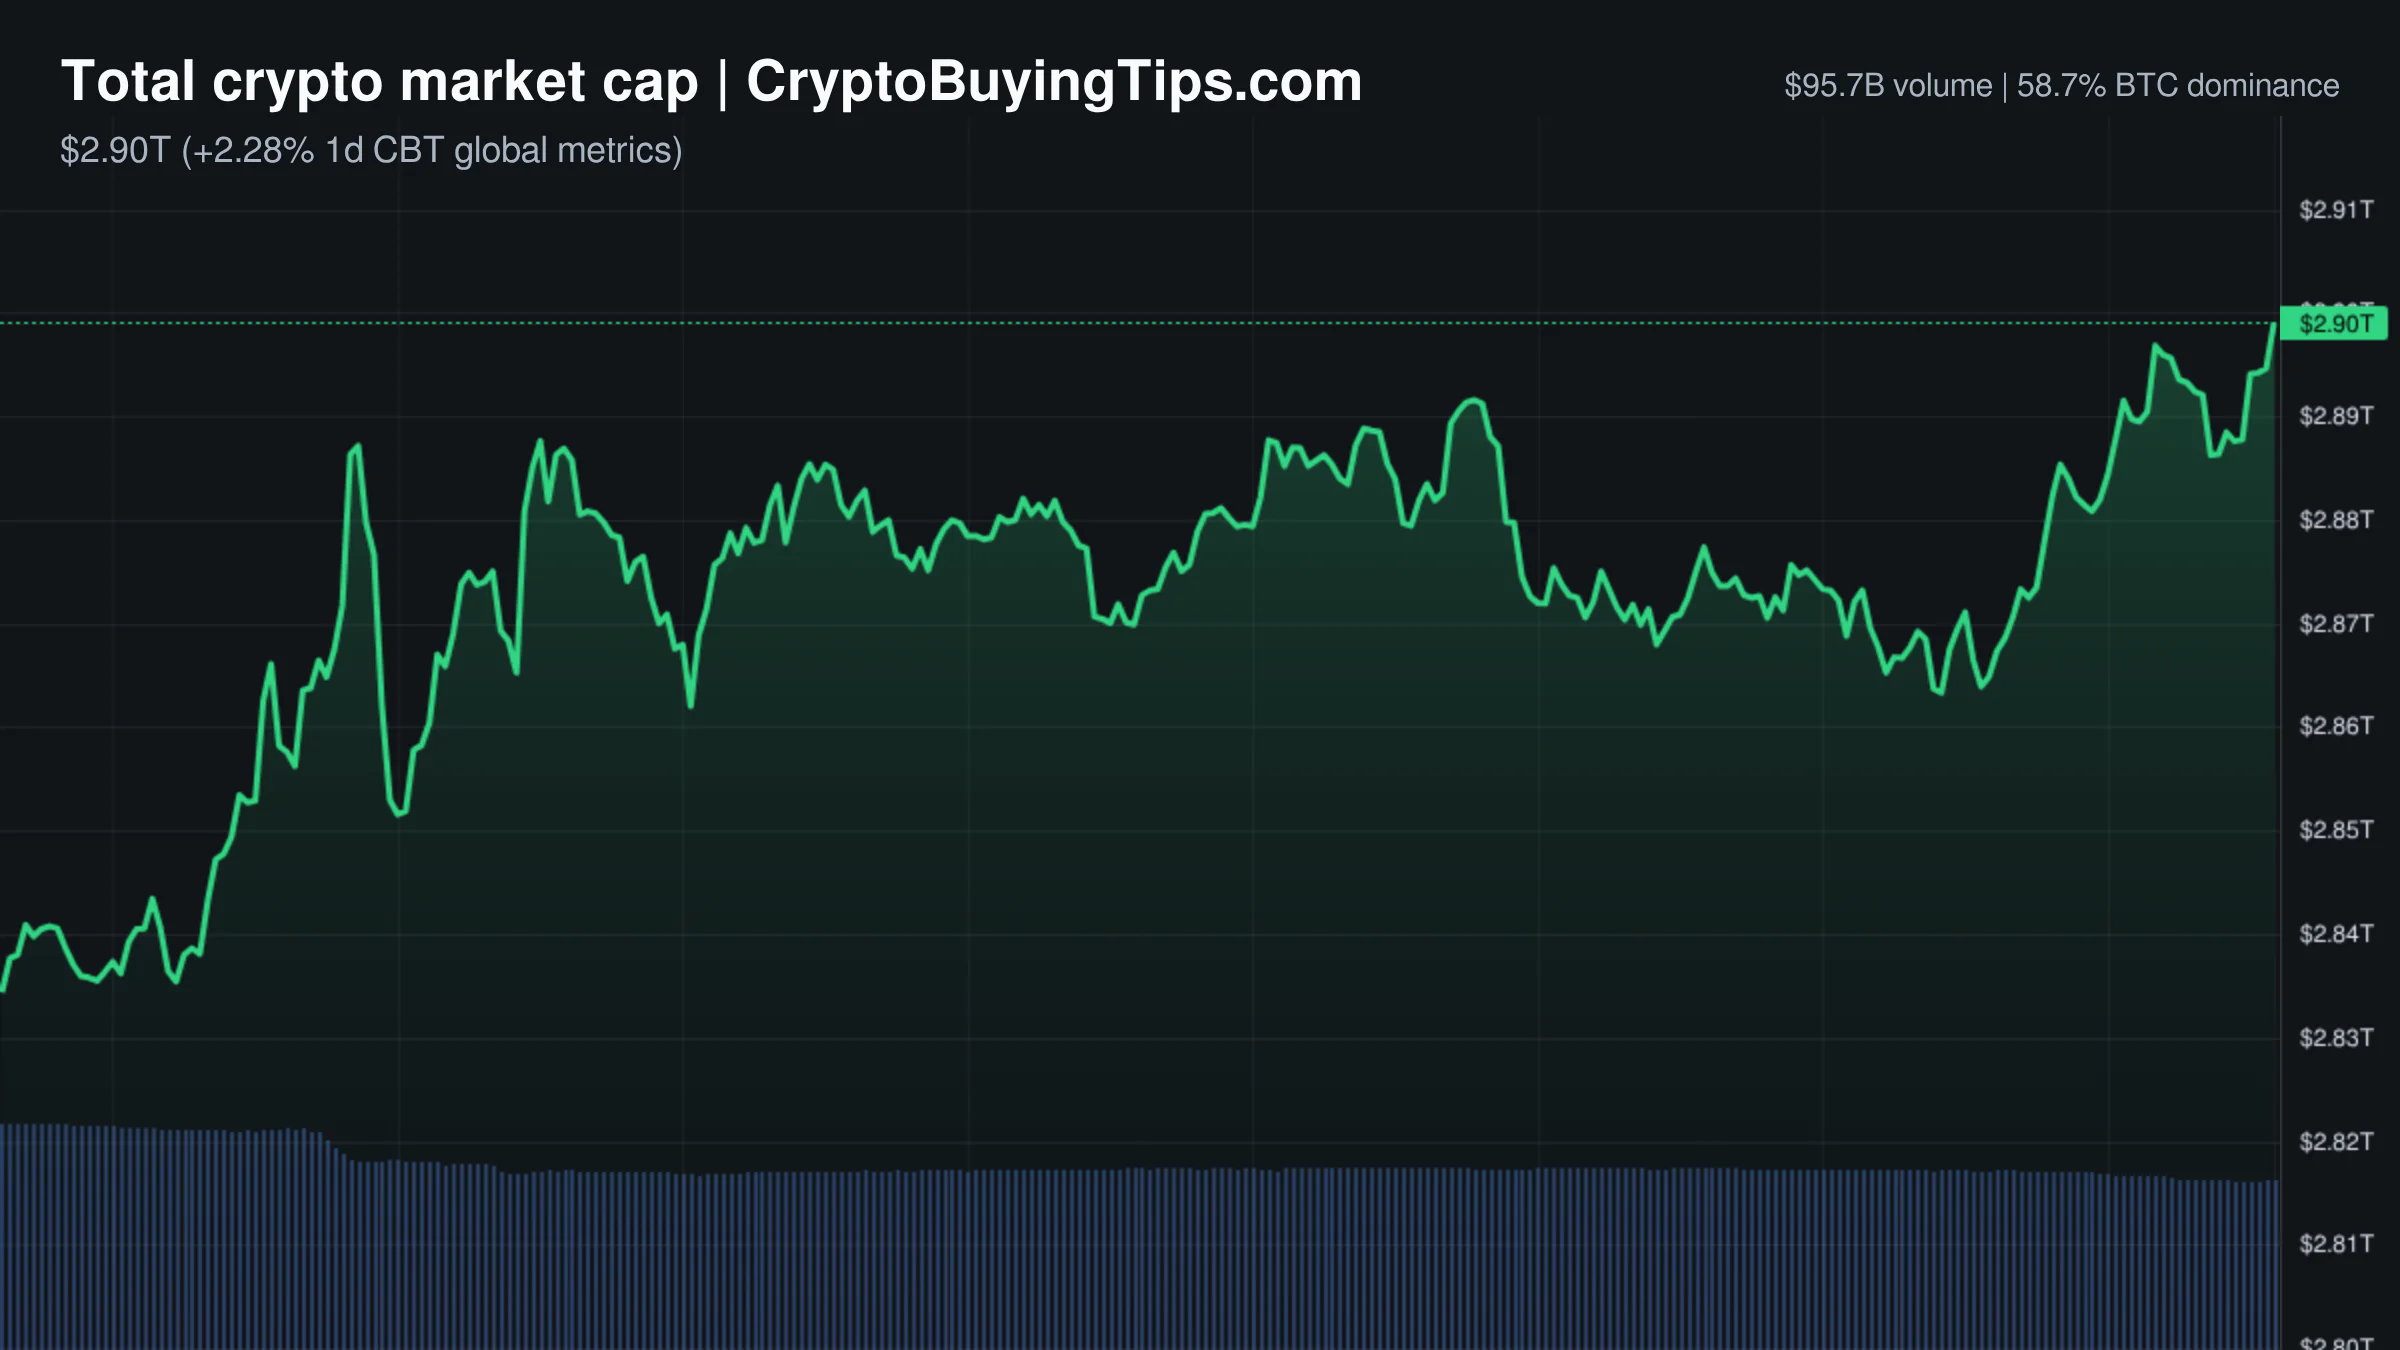
Crypto Market Overview | low volume rally meets high leverage and fed stablecoin rules | September 25, 2026
The market shows high leverage despite low spot volume; see our read on the Fed, BTC action, and altcoin rotation for…
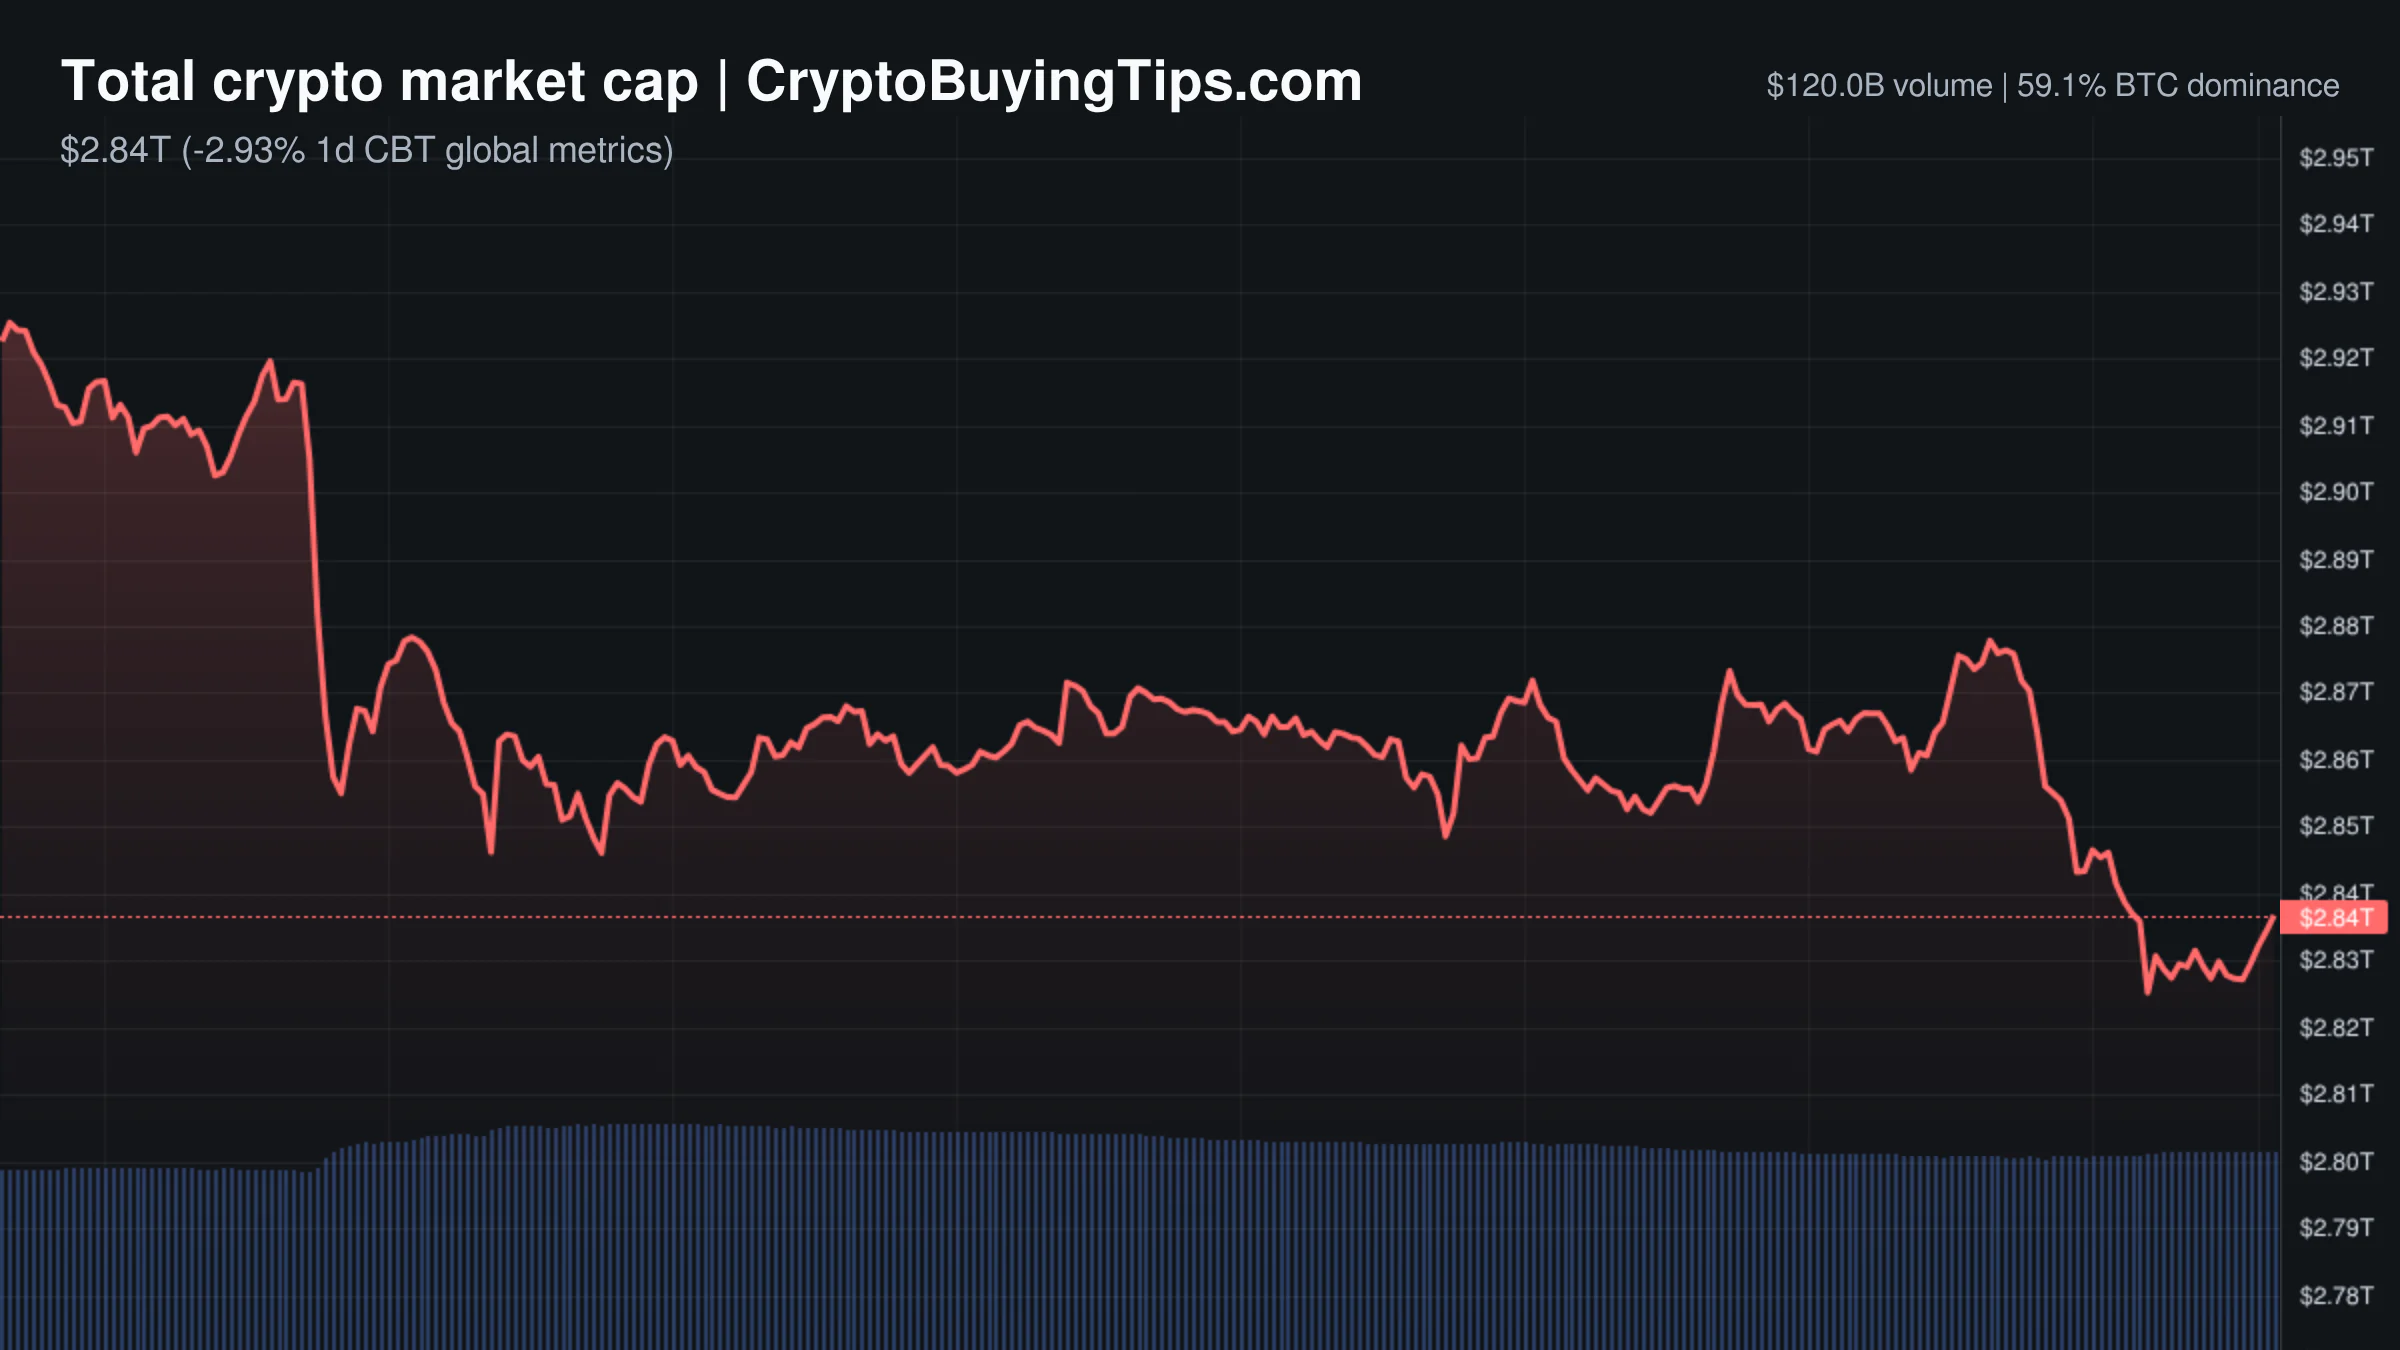
Crypto Market Overview | leveraged flushes and institutional tokenization rails collide | September 24, 2026
The crypto market sees leveraged flushes amid institutional tokenization rails; see our overview of BTC dominance and…
Stablecoin volume just eclipsed spot trading. Here is where the money is hiding
Stablecoin volume now exceeds total spot trading, which suggests capital accumulation rather than a full exit from…
Crypto Market Overview | Leveraged bets drive gains amid diverging us regulatory paths | September 19, 2026
Leveraged bets drive crypto gains amid diverging us regulatory paths; see our market overview on BTC, ETH, and macro…