
Are crypto perpetual futures legal in the US? The CFTC just licensed two venues to find out
Are crypto perpetual futures legal in the US? For years the honest answer was a shrug and a terms-of-service page. This week it became a yes, with paperwork attached. We previously covered crypto exchanges reverse bridge for more background.
CFTC Chairman Michael Selig announced on November 16 that the agency had approved a firm as both a designated contract market (an exchange) and a derivatives clearing organization (a clearinghouse), using blockchain-based execution and settlement. The statement didn't name the firm, but Disruption Banking reports that the registration order for TLD Clearing, Inc., doing business as Backpack Clearing, is dated November 13. tZERO's exchange license came a week earlier. Selig is currently the agency's only sitting commissioner, so at least the vote count was easy.
Our news scoring system rated this story 10/10 novelty, which is as high as it goes. The interesting part is where it lands, and that isn't the headline.
Are crypto perpetual futures legal in the US now, and for whom?
Legal on licensed venues, yes. Legal everywhere, no. The distinction matters more than the headline suggests.
Offshore perp venues have run the show for years, and US customers were generally supposed to stay away from them. What's new is a domestic route: perps listed on a CFTC-designated exchange and cleared through a CFTC-registered clearinghouse. CoinPerps puts the trade-off plainly: US traders can now use regulated perpetuals, though with lower leverage and fewer markets than offshore venues.
That's the bargain. You give up the menu and the leverage dial, and in return you get a counterparty with a regulator attached.
What we can't tell you from our research is how a typical American retail account actually reaches these venues, what the leverage caps are, or which collateral each one accepts. Those details decide whether "legal" means "available to you on Tuesday." We'd treat anyone who claims to know as having read a different pack than ours.
What a clearinghouse changes
An exchange matches orders. A clearinghouse stands in the middle of every trade, collects margin from both sides, and is supposed to make good if one side can't pay. The DCO rulebook is 17 CFR Part 39, and it is dense, procedural and not remotely exciting. That's the point of it.
Compare that with the typical offshore perp venue, where your protection is the exchange's balance sheet and its mood. Regulated clearing swaps that for margin rules and default procedures written down in advance.
The onchain settlement is the novelty. Selig himself called it "a regulated pathway for a new generation of market infrastructure built using blockchain technology." Whether that makes settlement faster or merely more fashionable is something the next few months of volume will answer.
A market that was already 91.7% derivatives
Here is the second layer. The CFTC didn't license a niche product. It licensed the product that already is the market.
The market metrics we track put 24h derivatives volume at $832.77B, up 13.94%, against $75.22B in spot, up 4.09%. That makes derivatives roughly 91.7% of combined spot and derivatives volume, or about 11x spot.
Open interest tells a sharper story. Perpetual open interest is $330.84B, about 15.0% of the $2.20T total crypto market cap. Dated futures open interest is $1.03B. Divide one by the other and perps are about 321x futures ($330.84B / $1.03B = 321.2).
For a US regulator, that ratio is awkward. Traditional dated futures are the product American venues have long been able to list, and they hold a rounding error of the positioning. Perps hold nearly all of it. Our news scoring system rated this story 7/10 for macro impact, and this is why: regulated access to perps is regulated access to where the leverage lives.
Our read is that it's a structural story, not a price catalyst. Backpack and tZERO are new, and we have no volume figures for either, so nobody should be modelling this as a flood of American money arriving tomorrow.
Fear on the screen, leverage in the volume
The mood and the activity don't match. The Fear & Greed Index reads 13/100, extreme fear, yet total market cap is flat at +0.15% and both the CMC20 and CMC100 are slightly positive. Prices aren't confirming the panic. Derivatives volume is still growing about three times faster than spot.
We can't say who is on the other side of that volume. Funding rates and liquidation data didn't load in our feeds today, so we won't guess whether leverage is leaning long or short. What the volume does show is that the appetite for leveraged exposure hasn't gone anywhere while sentiment sits near the floor. That is precisely the environment in which a regulated route matters: the traders already exist, and they're already using the product.
Where the headline runs ahead of the facts
A few caveats, none of them dramatic.
Regulated doesn't mean safe. A clearinghouse protects the system from a counterparty failing; it does not protect your margin from a bad trade, and lower leverage on a 13/100 sentiment day is a feature, not an insult.
The agency is also running on one commissioner, with the Senate Agriculture Committee preparing to consider two nominees, per Disruption Banking. Rules made under a one-person commission can be revisited by a bigger one, and that's worth remembering before anyone calls this settled.
And "approved" describes a licence, not a market. Liquidity on a new venue starts at zero and has to be earned, which is why offshore books are still where the depth sits.
Where we land
If you're a US trader, the practical change is that a domestic, rules-based route to perps now exists, and you should judge it on boring things: margin terms, collateral, onboarding, and whether the order book is deep enough to trade without moving it. If you've been trading offshore, the regulated option is a different product with different trade-offs, not a drop-in replacement.
We previously covered how US crypto perps were reported as opening back in May. What's new now is two named venues holding both licences, and that's the point at which a headline starts turning into something you can actually use.
Some links in this article may be affiliate links. We may earn a commission at no extra cost to you — this never influences our analysis or coverage.
Sigrid Voss
Crypto analyst and writer covering market trends, trading strategies, and blockchain technology.
More Articles
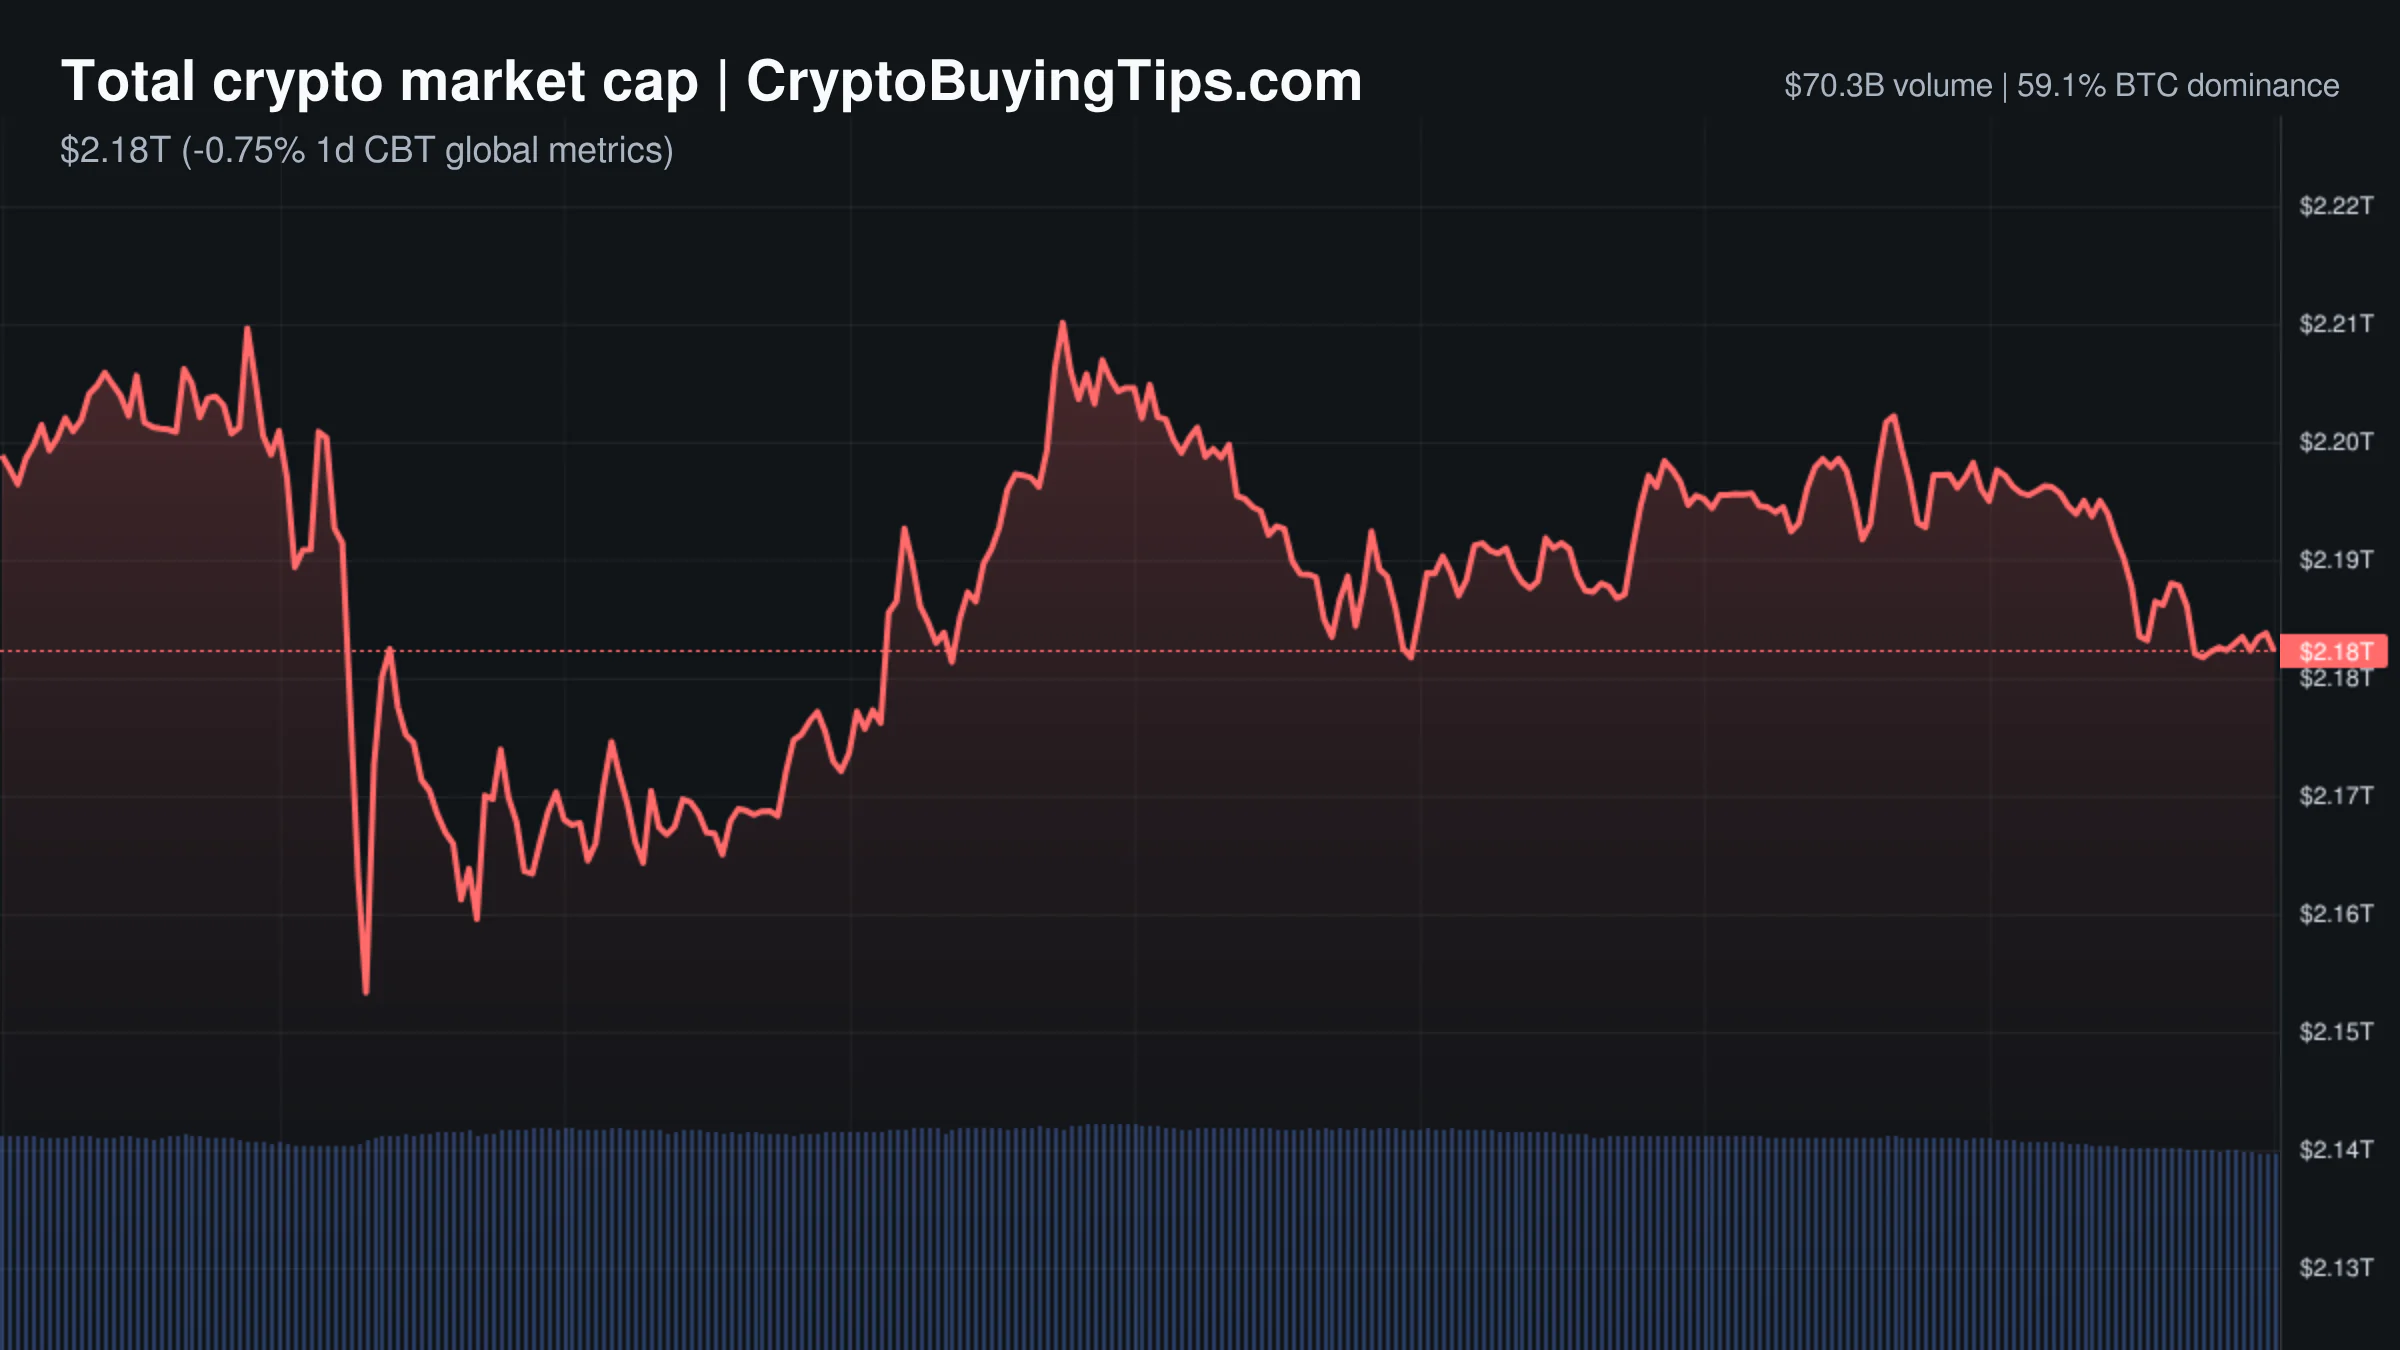
Crypto Market Overview | Extreme fear and heavy derivatives leverage as spot volume declines and Bitcoin tracks risk assets | November 18, 2026
Bitcoin trades near $64,190 amid extreme fear as spot volume declines. Derivatives volume is up 9.03%, showing heavy…
What is implied volatility in crypto? ETH's reads 13.8 points hotter than Bitcoin's
Price charts are just yesterday's weather reports. Implied volatility offers a look at what traders are actually betting…
Crypto Market Overview | Extreme fear and equity weakness as derivatives dominate volume amid a soft market cap | November 17, 2026
The Fear & Greed Index hits extreme fear as derivatives dominate volume. We analyze the soft market cap, rising…
Crypto Market Overview | volume surges amid geopolitical risk and institutional outflows | November 9, 2026
Crypto volume surges amid geopolitical risk and institutional outflows; see how BTC dominance shifts while altcoins…