
What is implied volatility in crypto? ETH's reads 13.8 points hotter than Bitcoin's
A price chart tells you what already happened, which is a bit like reading yesterday's weather report and calling it a forecast. Implied volatility is the closest thing the market has to tomorrow's. So what is implied volatility in crypto, and why does Ethereum's reading sit 13.8 points above Bitcoin's? In short, it's a number extracted from options prices that shows how large a move traders are paying to protect against. Volmex has it at 61.61 for ETH and 47.77 for BTC. We previously covered Bitcoin ETF flows for more background.
What is implied volatility in crypto, and how does it work?
An option is a contract that pays off if price moves far enough in the right direction before expiry. Its price has two parts: how much it's already worth, and how much you're paying for the chance that it becomes worth more. That second part, the time value, rises when traders expect bigger swings. Feed the option's market price into a pricing model such as Black-Scholes, solve backward, and out comes the volatility the market is implying. Neutralis describes it as the annualized volatility that reconciles an option's market price with a theoretical model.
Historical (or realized) volatility measures how much price actually moved. Implied volatility measures how much traders are pricing in for what comes next. One is a rear-view mirror and the other is a bet.
Because the figure is annualized, it needs translating. A common rule of thumb divides it by the square root of 365 (about 19.1) to get a typical one-day move. Our calculation:
- ETH at 61.61 implies roughly 3.2% a day, about $57 on a price of $1,779.14.
- BTC at 47.77 implies roughly 2.5% a day, about $1,597 on a price of $63,875.02.
Treat those as rough. The shortcut assumes returns follow a tidy bell curve, and crypto has never once behaved tidily. Real tails are fatter.
Reading the ETH versus BTC volatility gap
The spread is 61.61 minus 47.77, or 13.84 points. Put differently, 61.61 divided by 47.77 is about 1.29, so ETH options are priced for swings roughly 29% larger than BTC's (our calculation).
One figure in our data could be misread here. The 0.0279 ratio is the ETH/BTC price ratio (1,779.14 divided by 63,875.02), not a volatility ratio. It's context rather than the signal. ETH is a small slice of the market (10.01% dominance) and trades at a modest fraction of Bitcoin's price, while the options market says it should be the bumpier of the two.
What the premium doesn't say is direction. Implied volatility goes up when traders buy protection against a drop and when they buy upside calls. It says "bigger move expected," not "down" or "up." Anyone who reads a high IV as a sell signal is reading something the number never promised.
Nor does it come from network activity. ETH gas on our feed sits at 0.4 to 0.52 Gwei, which means on-chain fee demand is close to nothing. The premium is about uncertainty over price, not busy blockspace. We previously covered a similar Ethereum and Bitcoin risk gap if you want the earlier version of this setup.
There is also a gap in our own data. Judging whether options are expensive means comparing implied volatility with what the asset has actually done. That difference is the volatility risk premium, which FinanceFeeds defines as the gap between implied and realized volatility. We don't have a realized figure or a history for this spread in today's feed, so we can't say whether 13.8 points is wide by its own standards. Anyone who tells you it is, with confidence, is working from data we haven't seen.
How does the options premium compare with the VIX?
The VIX is the same idea applied to the S&P 500: implied volatility backed out of index options. It's at 27.07, while SPY is down 1.40% and QQQ down 1.50% on our feed.
Setting the numbers side by side gives BTC at about 1.8 times the VIX and ETH at about 2.3 times (our calculation). Don't read much into that. Crypto has a structurally higher volatility level than equities, so the useful question is whether the two gauges move together. A 2019 ScienceDirect study found substantial correlation between crypto volatility and products like the VIX and VSTOXX during elevated implied-volatility episodes. A VIX at 27.07 alongside crypto IV in the high 40s and low 60s is consistent with a market that's nervous across the board rather than one that's panicking in a single corner.
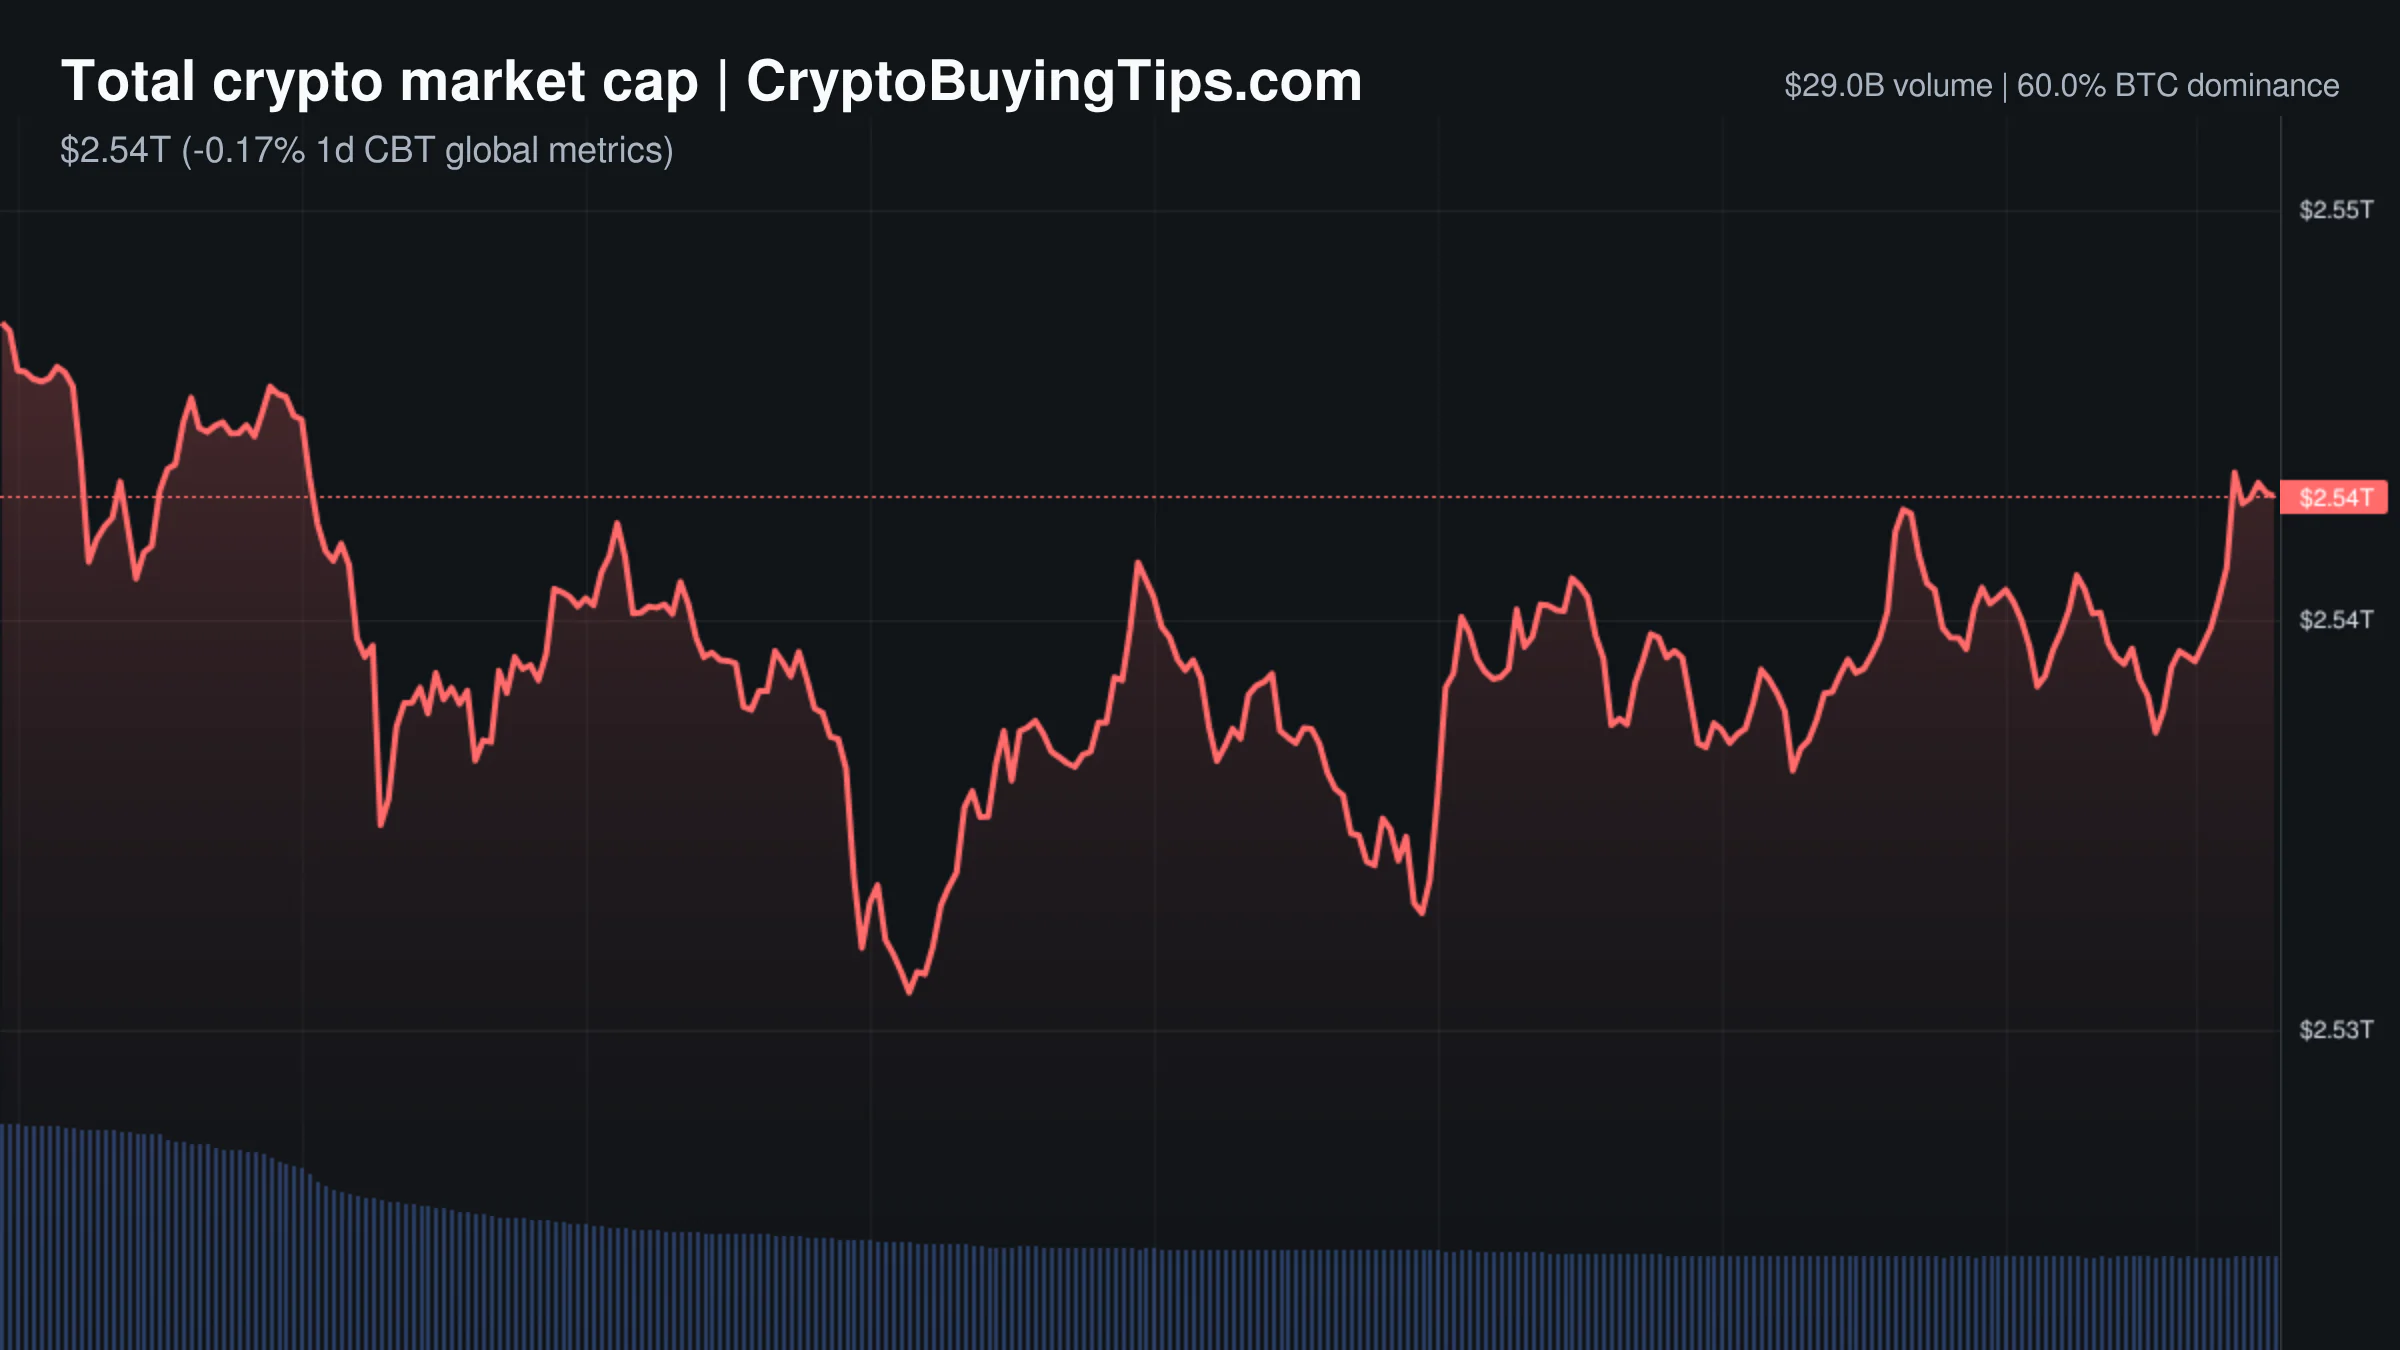
Then there's leverage, which options prices don't capture directly. Perpetual open interest is $322.9B, about 14.9% of the $2.17T total market cap (our calculation), and derivatives volume runs roughly 9.8 times spot. When that much borrowed money sits on one side or the other, a move that options traders priced as ordinary can overshoot. The liquidation figures that would size the risk didn't load today, so we're treating them as unknown rather than zero.
Where people get tripped up
- Treating IV as a forecast. It's a price set by buyers and sellers, and sellers of volatility are wrong regularly.
- Reading it as bearish. High implied volatility only says traders expect a larger move.
- Comparing numbers from different providers. Volmex, Deribit's DVOL and exchange-specific gauges use different methods, so a 61 on one isn't a 61 on another.
- Looking at one reading with no history. A snapshot tells you the level; the trend and the comparison with realized volatility tell you whether it means anything.
What to take from it
The practical use is simple. When ETH's implied volatility sits well above Bitcoin's, as it does now, you're being told the market expects Ethereum to be the more violent of the two. That's worth knowing before sizing a position, setting a stop, or deciding how much of a portfolio can sit through a 3% daily wobble without anyone losing sleep.
Our read is that the gap is real information about expected turbulence, and that it's less information than most commentary will claim. Direction, timing and realized volatility aren't in it. Check the VIX, check the leverage, and keep in mind that an options desk pricing in a big move has, on occasion, been confidently wrong about which way.
Some links in this article may be affiliate links. We may earn a commission at no extra cost to you — this never influences our analysis or coverage.
Sigrid Voss
Crypto analyst and writer covering market trends, trading strategies, and blockchain technology.
More Articles
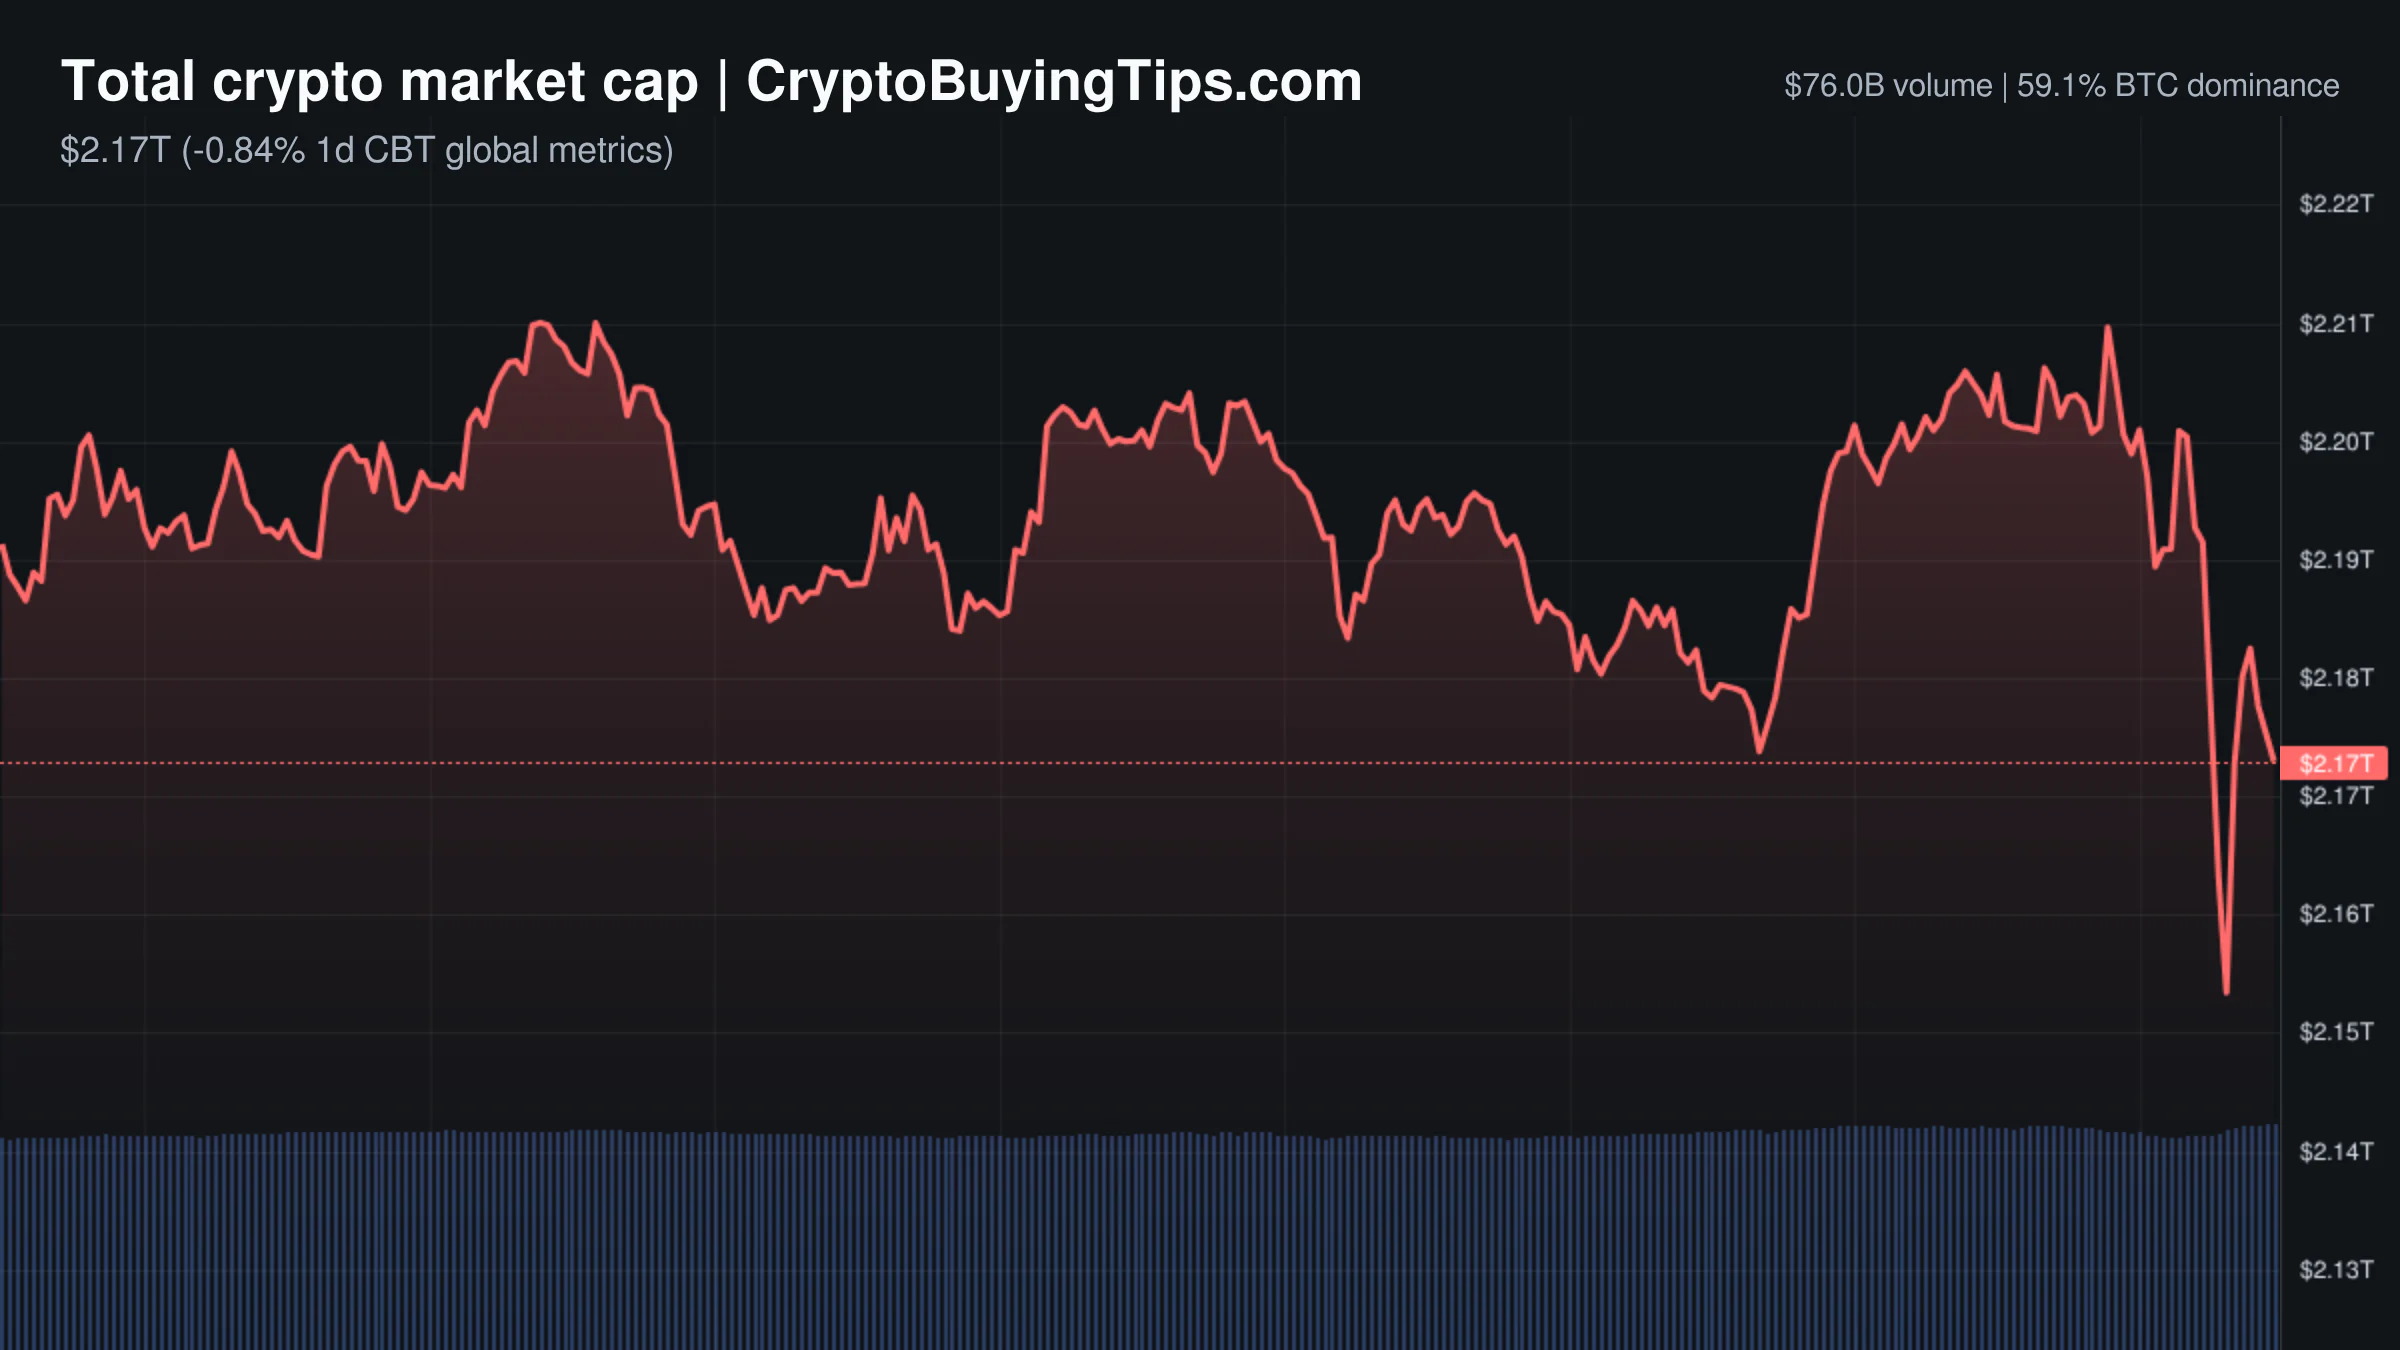
Crypto Market Overview | Extreme fear and equity weakness as derivatives dominate volume amid a soft market cap | November 17, 2026
The Fear & Greed Index hits extreme fear as derivatives dominate volume. We analyze the soft market cap, rising…
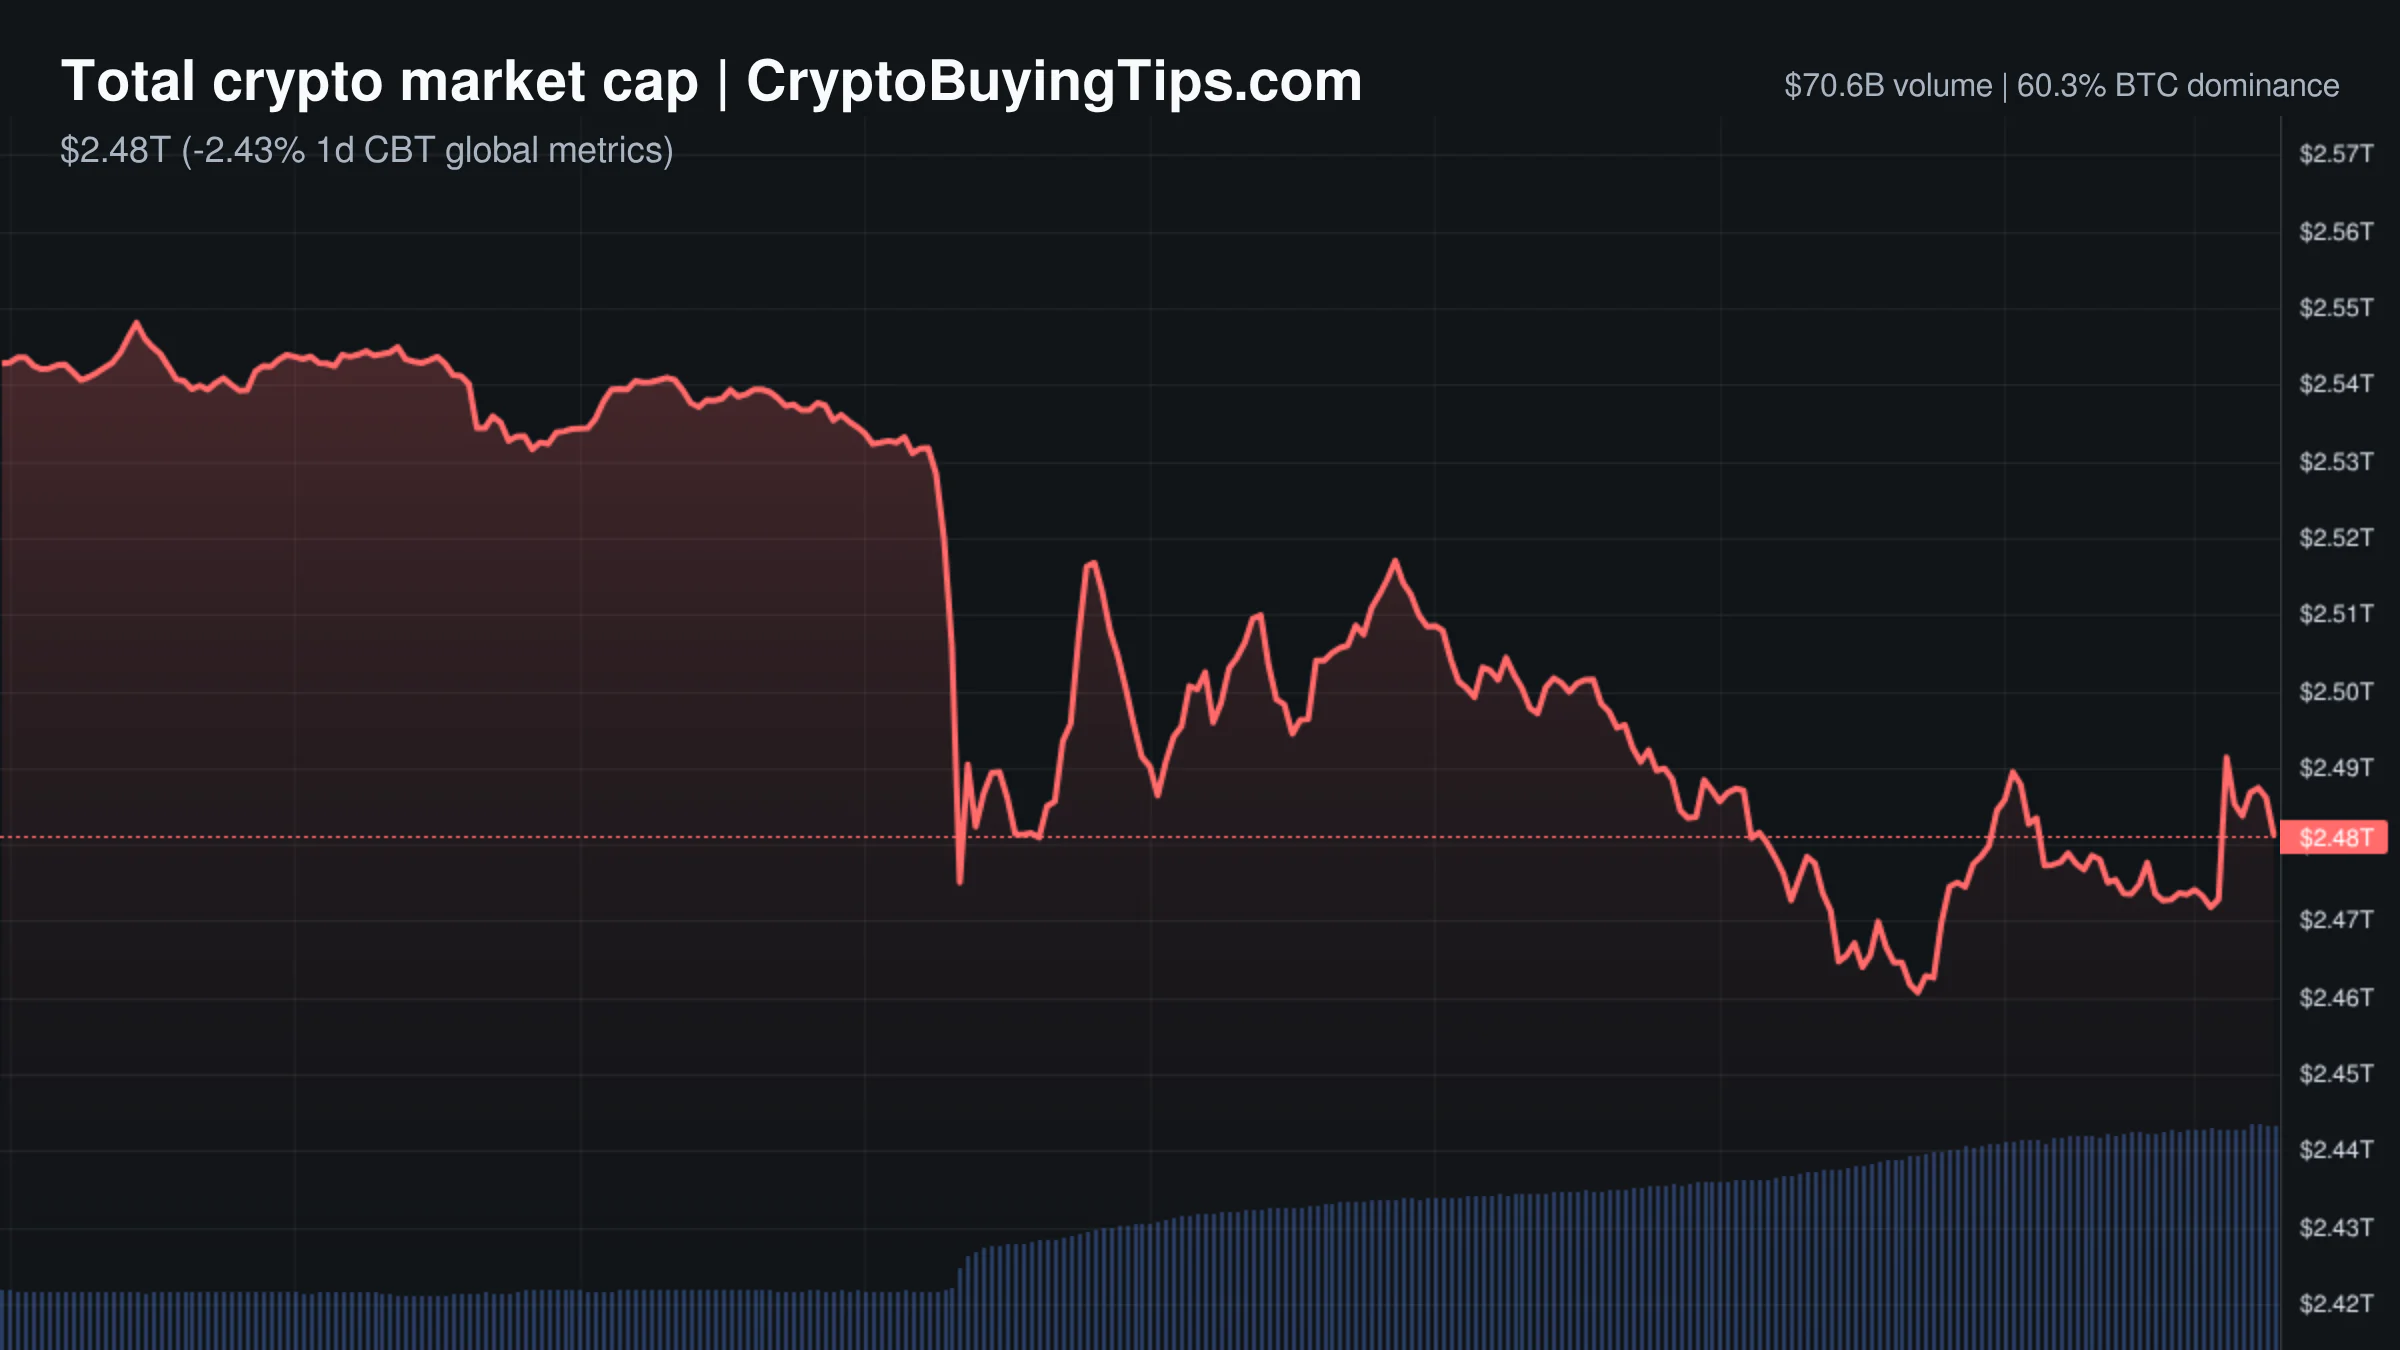
Crypto Market Overview | volume surges amid geopolitical risk and institutional outflows | November 9, 2026
Crypto volume surges amid geopolitical risk and institutional outflows; see how BTC dominance shifts while altcoins…
Vitalik wants Ethereum to be a store of value because the gas data says he has to
The narrative shift from transaction utility to store of value seems rather convenient given current gas fees. With…
Crypto Market Overview | volume collapse amid regulatory heat hitting centralized exchanges | November 8, 2026
Crypto market overview shows volume collapse amid regulatory heat hitting centralized exchanges; see why liquidity is…