
BlackRock and Visa are now validators, and Circle just built a walled garden for banks
The news that BlackRock and Visa are validators on a new stablecoin layer suggests institutional money is building infrastructure before the public even sees it. While most outlets are reporting the launch of the Arc mainnet as a simple product update, our read is that this is a systemic shift. Circle isn't just adding a feature; they are building a permissioned environment for liquidity that looks less like a public blockchain and more like a digital version of the existing banking system. If you are wondering what is circle arc mainnet, it is effectively a regulated settlement layer for USDC that allows the biggest players in finance to move money without the friction (or the transparency) of public DeFi. We previously covered Open USD stablecoin for more background.
How does what is circle arc mainnet work?
At its surface, Arc is an open Layer 1 blockchain purpose-built for financial markets and real-time money movement [circle.com]. It integrates directly with Circle's existing platform and uses USDC as the native gas token [blockonomi.com]. Instead of relying on a decentralized swarm of anonymous miners or stakers, Arc is secured by a founding cohort of institutions that already run the world's financial plumbing [businesswire.com].
Our news scoring system rated this story 10/10 for novelty because it represents a departure from the "permissionless" ethos of crypto. Most stablecoin launches focus on how to get more retail users or how to integrate with a new DeFi protocol. Circle is doing the opposite. They are building a dedicated rail for banks, asset managers, and payment networks [decrypt.co]. This is not about expanding the crypto ecosystem; it is about absorbing the utility of blockchain into a controlled, institutional framework.
Why the institutional validators matter
The inclusion of names like BlackRock, Visa, Mastercard, and the DTCC as validators lends immediate credibility to the network [decrypt.co]. For a traditional bank, the risk isn't just the volatility of an asset, but the "who" behind the network. By putting the DTCC and BlackRock in charge of validation, Circle has removed the identity risk that usually keeps these firms away from public rails.
This move happens against a backdrop of institutional hesitation in the spot markets. Our market data tools show that US spot Bitcoin ETFs recently extended their outflows to a second day with a $295.9 Million exit. It is a curious contradiction. While institutional capital is flowing out of spot BTC ETFs, the very same institutions are stepping up to validate the infrastructure for the next generation of stablecoin settlement.
The goal here is regulated settlement rather than speculation. These validators aren't looking to trade memes; they are looking for a way to move billions of dollars in tokenized assets without worrying about who else is seeing the transaction or who might be censoring the block.
How this changes the stablecoin narrative
For years, the narrative has been that stablecoins would "disrupt" banking. Arc suggests a different outcome: stablecoins are simply becoming the new backend for banking. By creating a dedicated rail for large-scale capital movement, Circle is positioning USDC as the primary tool for institutional treasury management.
This shift toward permissioned liquidity pools is a pattern we have seen before. We previously covered how The US banning a digital dollar effectively outsourced the infrastructure to private players. Arc is the logical conclusion of that trend.
The data shows just how concentrated the market remains. Our metrics put BTC dominance at 58.35275725355006, which tells us that while the "crypto" market is dominated by one asset, the "utility" market is being carved up by a few massive entities. Our news scoring system again rated this shift as 10/10 for novelty because it signals the end of the "public rails or nothing" era.
What we are watching next
The real test for Arc will be the utility of the ARC token compared to the underlying USDC. If the ARC token becomes a requirement for institutional access, we could see a new form of "infrastructure rent" being paid by banks to Circle and its validators.
We are also keeping an eye on the "opt-in privacy" features currently in development [americanbanker.com]. The moment these banks can move money on a blockchain without the public being able to track the flow, the distinction between a public blockchain and a private database disappears entirely.
The adults have arrived, and they have brought their own rules. The gap between the decentralized dream and the institutional reality just got a lot wider.
Some links in this article may be affiliate links. We may earn a commission at no extra cost to you — this never influences our analysis or coverage.
Sigrid Voss
Crypto analyst and writer covering market trends, trading strategies, and blockchain technology.
More Articles
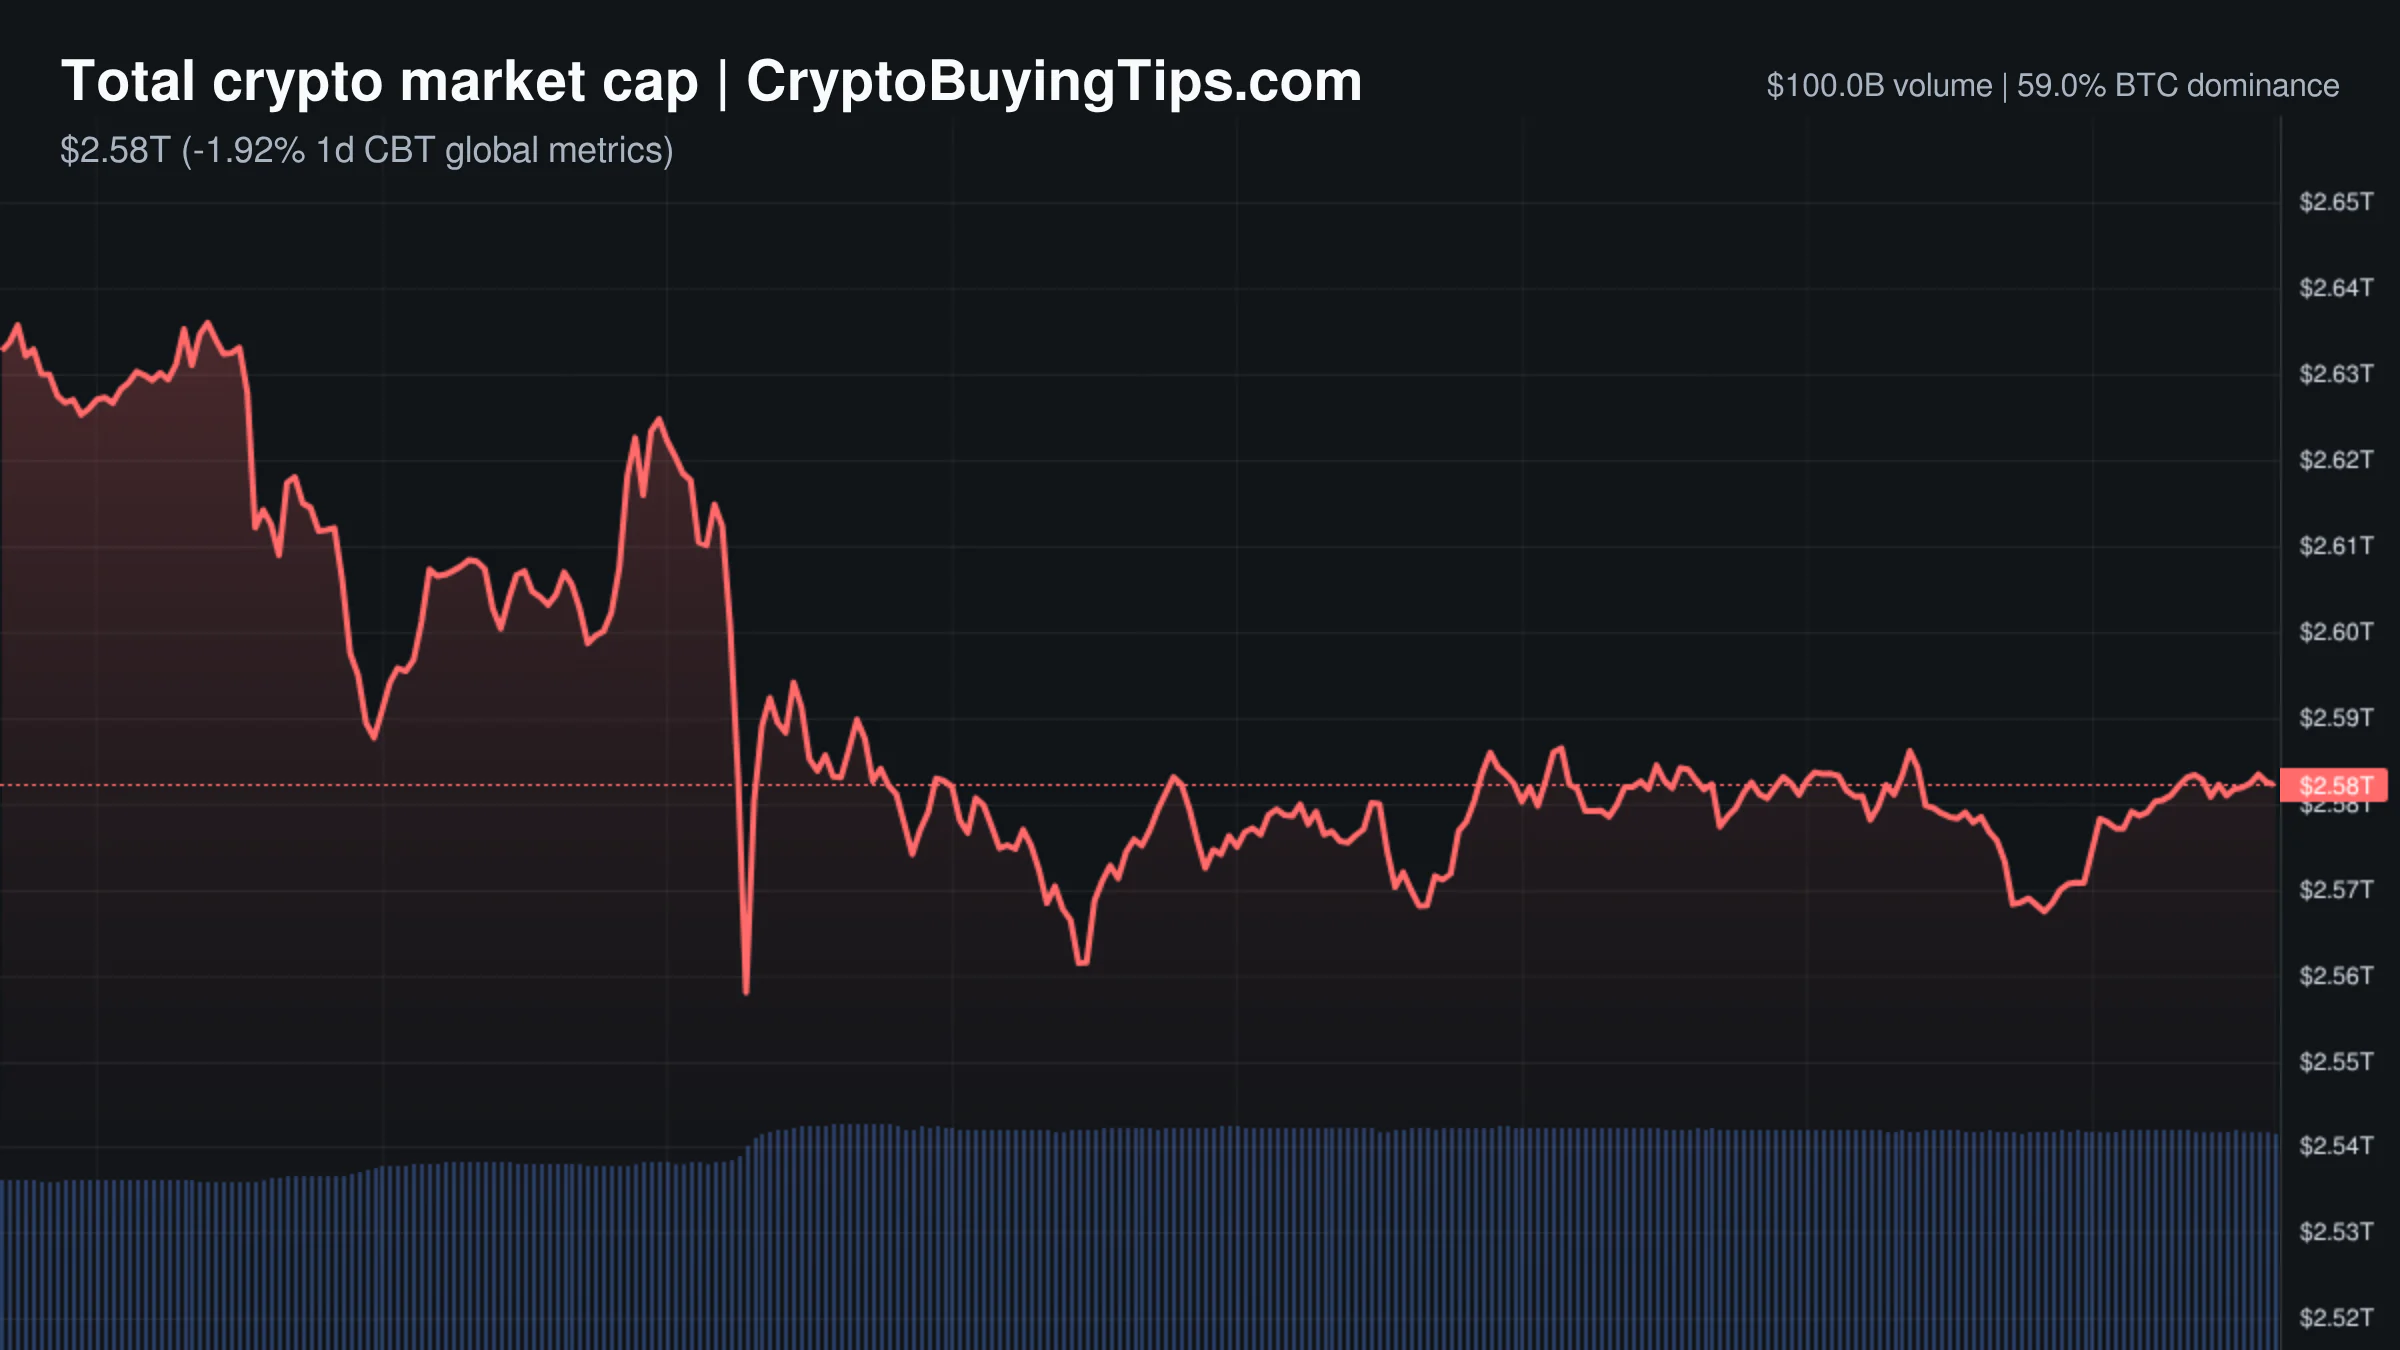
Crypto Market Overview | Regulatory setbacks and macro jitters trigger leveraged sell-off | September 16, 2026
Market jitters and regulatory setbacks caused a leveraged sell-off as total market cap dropped 4.34% despite high…
Ethereum gas is practically free. Our signal scanner thinks it's a coiled spring.
Ethereum's quiet fee structure suggests nothing has changed; it just means something big is about to happen on-chain.…
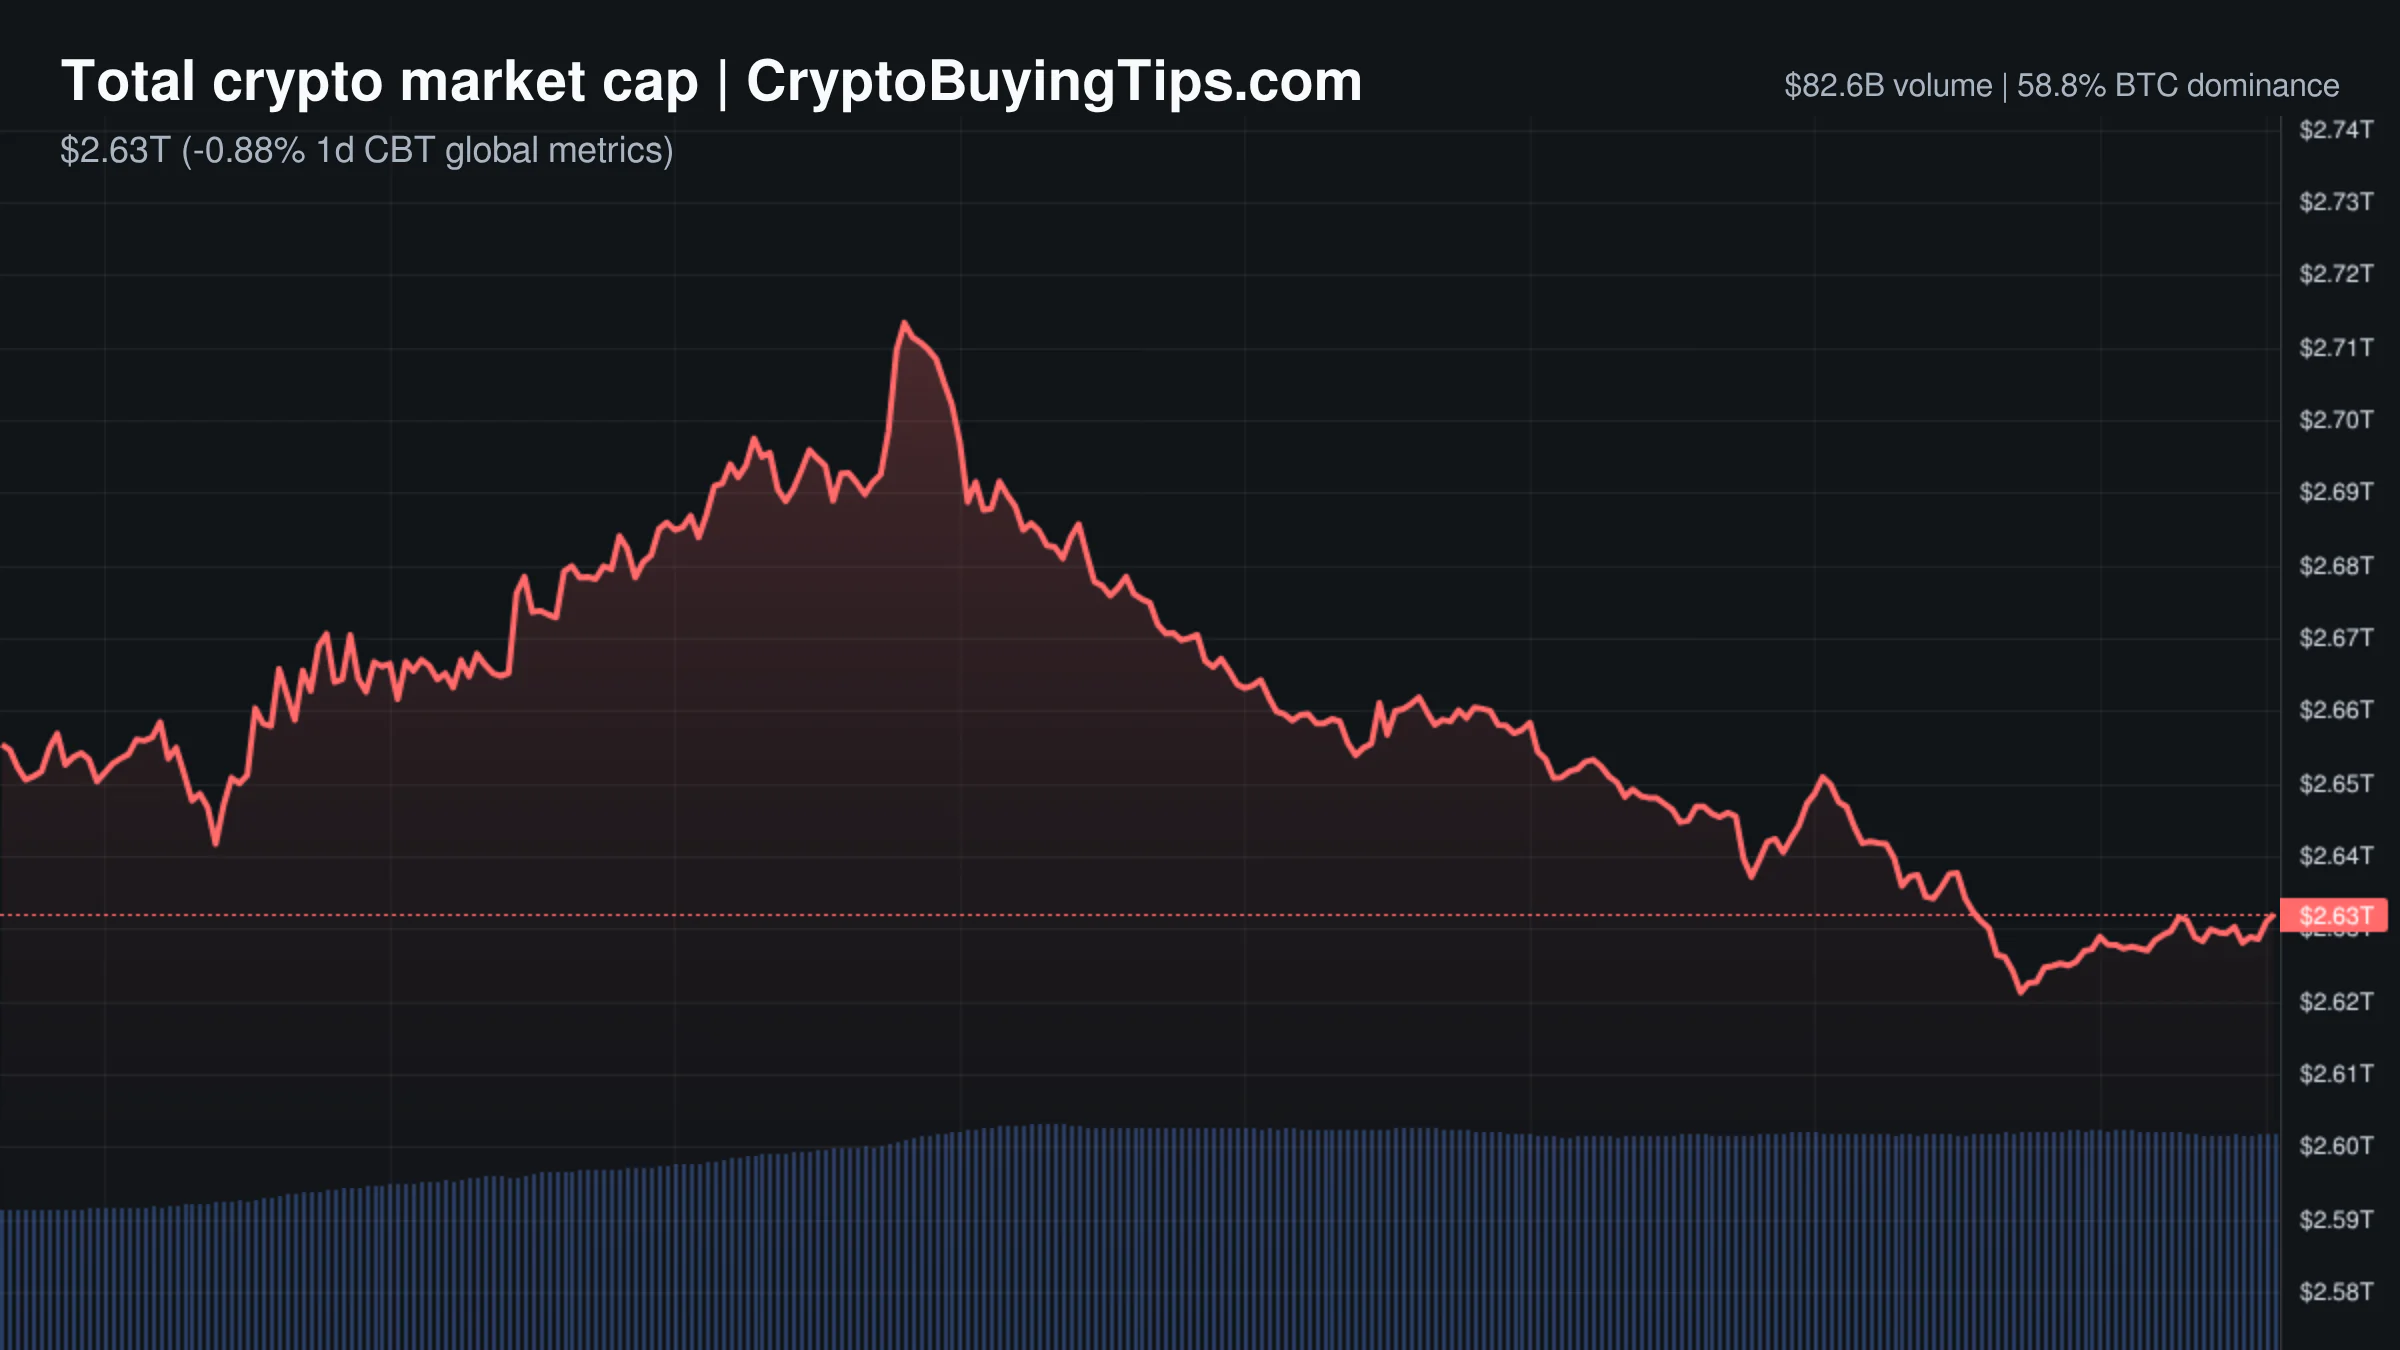
Crypto Market Overview | volume surges amid macro headwinds and regulatory uncertainty | September 15, 2026
Crypto market overview shows surging volume amid macro headwinds and regulatory uncertainty; see how BTC dominance holds…
Washington is still debating the dictionary while India tokenizes $620 billion
Washington debates semantics while Indian institutions tokenize $620 billion in corporate debt; this move shows how…